Down payments & PMI:
know your options.
Plan for the cash you need now, the payment you will make each month, and the savings you want to keep.
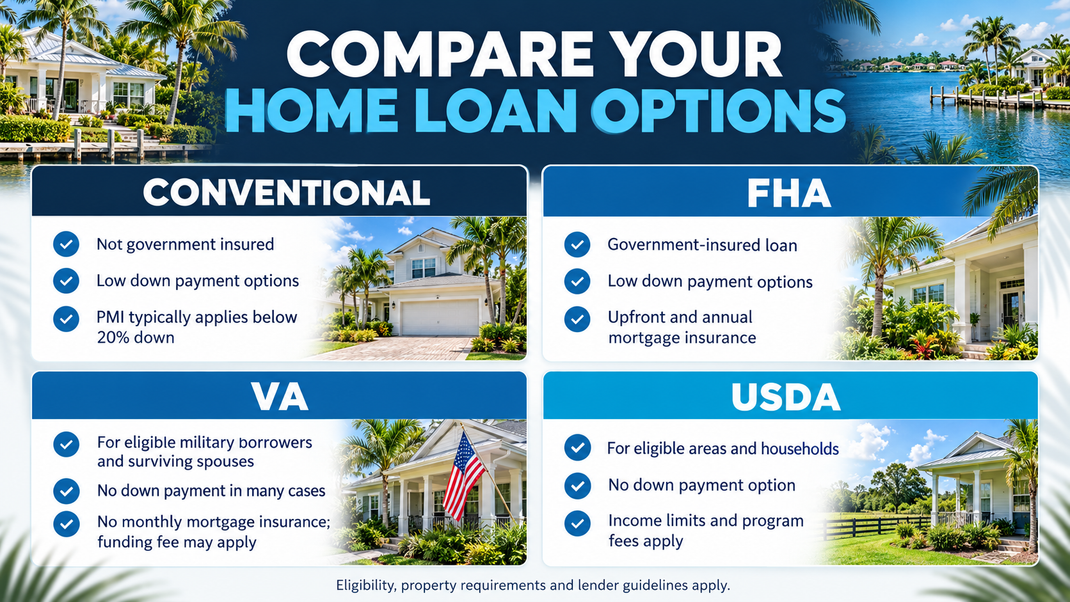
Compare your home loan options
Start with the programs you may qualify for. Ask your lender for a complete cost comparison based on your property and financial profile.
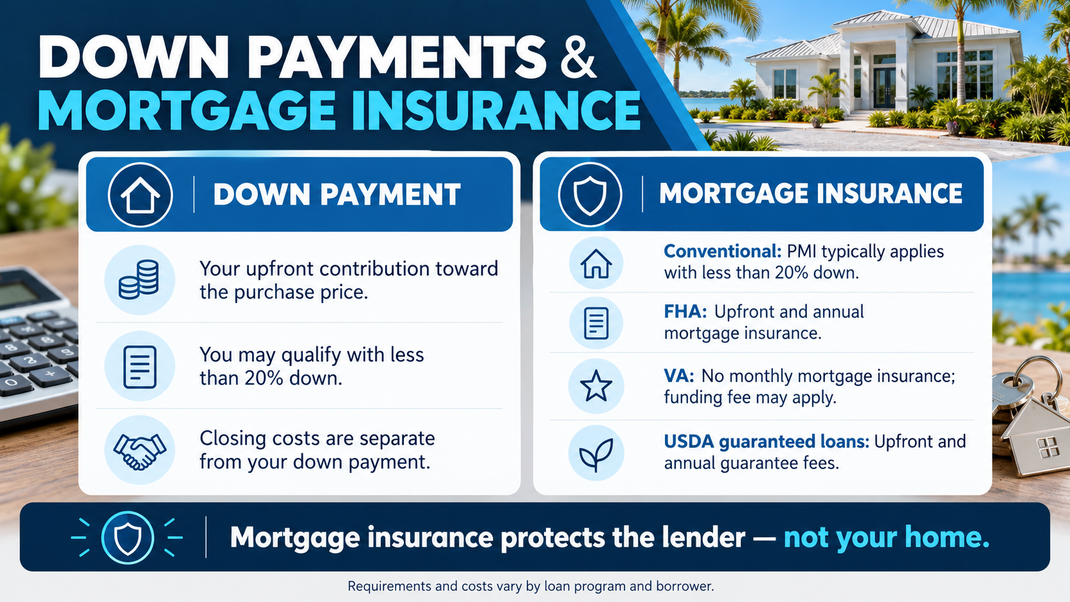
Understand the upfront and ongoing costs
Use this overview to see how the two fit into your homebuying budget.
Make a plan beyond the minimum
The right choice balances upfront cash, monthly costs and your remaining savings.
Choose a down payment that fits your budget
Borrow less. A larger down payment reduces your loan amount.
Keep reserves. Leave cash available for closing costs, moving, repairs and emergencies.
Compare the full payment. Include any mortgage insurance or program fees before choosing a loan.
Check how PMI is priced and paid
Costs vary. Your loan, credit profile and insurance arrangement affect the price.
Payment options vary. PMI may be paid monthly, upfront or through another structure. Ask how each arrangement affects your cash-to-close and ongoing payment.
Know when PMI can be removed
These general rules apply to many conventional loans covered by federal PMI cancellation requirements.
At 80% of original value: You can generally request cancellation when your balance reaches this point, subject to conditions. Ask your servicer about a written request, payment history and property-value requirements.
At the scheduled 78% point: Automatic termination generally occurs if your payments are current. This uses the scheduled balance, rather than a higher market value.
If your home value rises: PMI does not disappear automatically. Ask your servicer whether another cancellation route applies and what it requires.
Confirm where your funds can come from
Eligible sources may include savings, property sale proceeds, documented gifts and approved assistance. Loan program rules determine what is allowed and how it must be documented.
Gifts and loans are different. Disclose borrowed funds and confirm eligibility before accepting or transferring money.
Review assistance requirements
Check eligibility. Programs may have income, location, occupancy and homebuyer education requirements.
Understand repayment. Some assistance must be repaid. Funding can change, so confirm current availability and terms.
Calculate your complete cash-to-close
Include every category. Account for your down payment, closing costs, prepaid expenses and initial escrow deposits.
Request a complete estimate. Review the upfront total alongside your monthly payment and the savings you will have left.
Compare your down payment options
Speak with FHL Mortgages about the balance between upfront cash, monthly payments and reserves.
Educational information only; not an approval or commitment to lend. Program availability, costs and eligibility vary. FHL Mortgages is a DBA and mortgage department of Florida Homes & Loans Inc. | NMLS #2295908. Gemma Peterson | NMLS #2121526. Request secure upload instructions before sharing financial documents.