Mortgage Rates May Stay Above 7% Through 2027: What Buyers Can Do
Mortgage Rates May Stay Above 7% Through 2027: What Buyers Can Do
For the past few years, homebuyers have repeatedly heard the same advice:
“Just wait. Mortgage rates will come back down.”
But what if they don’t—at least not anytime soon?
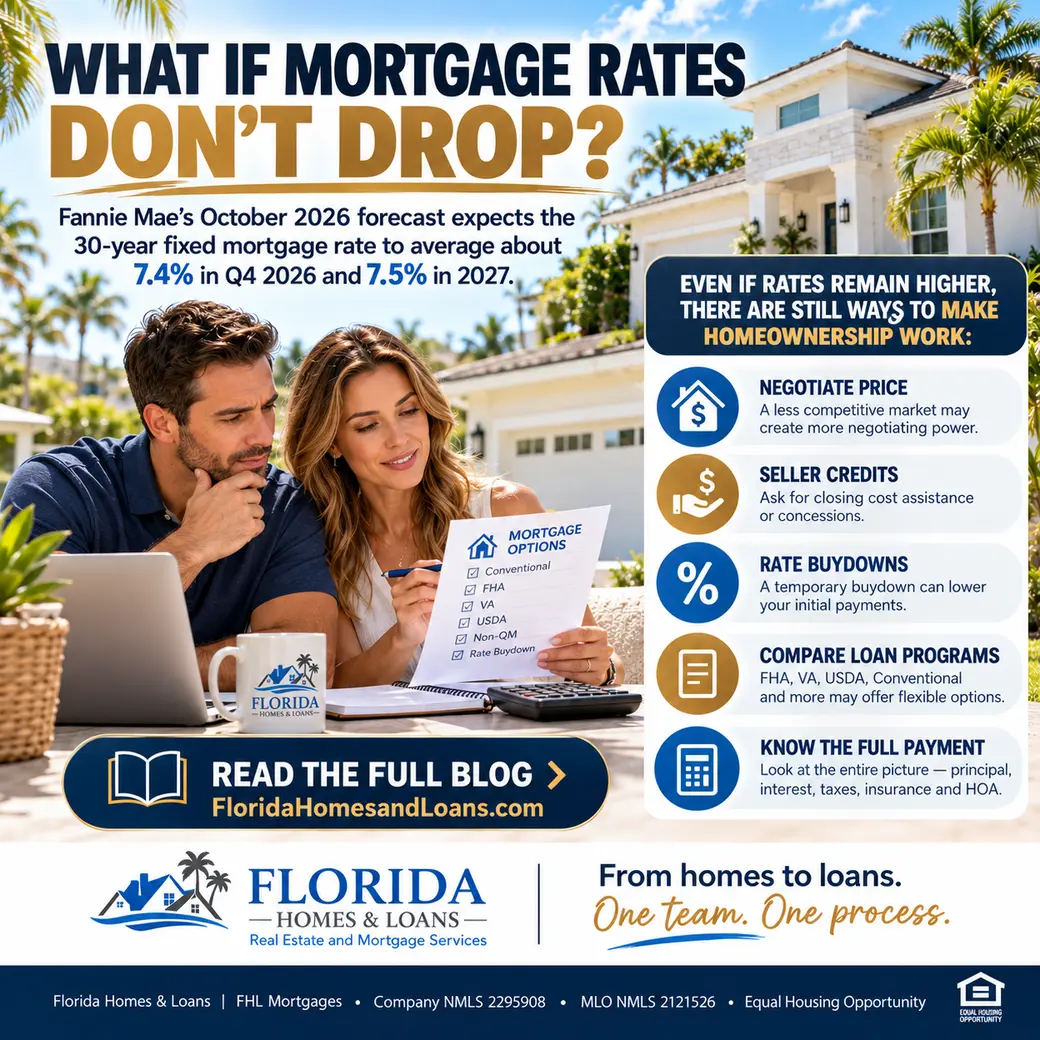
Fannie Mae’s October 2026 Housing Forecast now projects the average 30-year fixed mortgage rate at approximately 7.4% during the fourth quarter of 2026 and 7.5% throughout 2027.
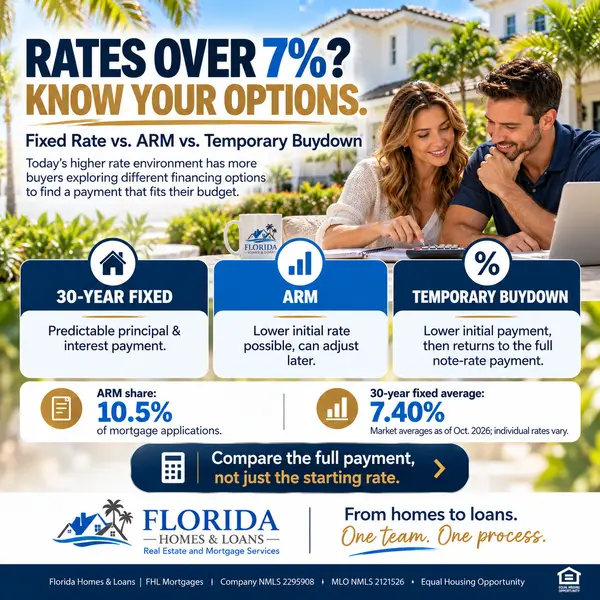
Meanwhile, Freddie Mac reported that the average 30-year fixed mortgage rate was 7.40% as of October 15, 2026.
That does not mean every borrower will receive a 7.40% rate. Individual mortgage rates vary based on the loan program, credit profile, loan amount, property, occupancy, points and other factors.
What it does mean is that buyers may want to stop building their entire homebuying plan around the assumption that dramatically lower rates are right around the corner.
The Forecast Has Changed Quickly
One of the biggest lessons from the mortgage market over the last several years is that forecasts can change.
Fannie Mae’s October outlook is significantly higher than its projections just one month earlier. Homes.com reported that Fannie Mae’s September forecast had anticipated approximately 6.8% for the fourth quarter of 2026 and around 6.7% for 2027.
That changed to 7.4% and 7.5%.
And that is exactly why buyers should be careful about making a major financial decision based solely on where someone predicts mortgage rates will be next year.
Forecasts are useful.
They are not guarantees.
“I’ll Buy When Rates Get Back to 5%”
We hear versions of this frequently.
And understandably so.
Lower mortgage rates would improve affordability and increase buying power.
But there is another question buyers should ask:
What happens if 5% rates do not return for several years?
Waiting could mean continuing to rent while also facing changes in:
-
Home prices
-
Property taxes
-
Insurance costs
-
Rent
-
Available inventory
-
Buyer competition
-
Personal income and finances
There is no guarantee that waiting produces a better overall deal.
Instead, buyers should determine whether purchasing makes financial sense based on the numbers available today.
Higher Rates Can Create a Different Kind of Opportunity
There is another side to a higher-rate market.
Some buyers leave the market.
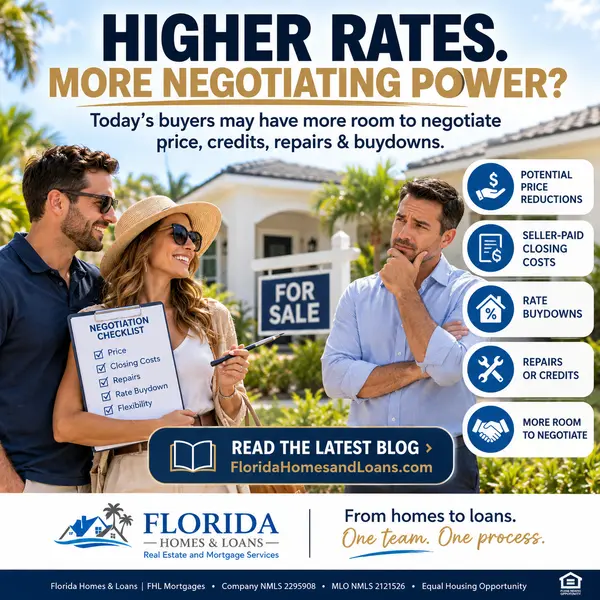
That can reduce competition and give the buyers who remain more negotiating power.
Instead of competing against multiple offers and automatically paying above asking price, buyers may have an opportunity to negotiate:
-
Purchase price
-
Seller-paid closing costs
-
Repairs
-
Repair credits
-
Temporary rate buydowns
-
Discount points
-
Closing timelines
-
Other contract terms
This does not happen on every property.
A highly desirable, correctly priced home can still attract significant interest.
But a property that has been sitting on the market, experienced price reductions or has a motivated seller may present an entirely different opportunity.
Look Beyond the Interest Rate
The mortgage rate is important.
But it is not the only number determining whether a home is affordable.
Your complete housing payment may include:
-
Principal
-
Interest
-
Property taxes
-
Homeowners insurance
-
Flood insurance, when applicable
-
Mortgage insurance
-
HOA or condominium fees
Two homes with the same purchase price and mortgage rate can have dramatically different monthly payments.
For example, one property may have much higher homeowners insurance or association fees.
Another may have a newer roof, lower insurance costs and no HOA.
That is why we encourage buyers to ask:
“What monthly payment am I comfortable with?”
Rather than:
“What is the maximum purchase price I qualify for?”
Those are not the same question.
Seller Credits Could Matter More Than You Think
When buyers negotiate, the first instinct is often to ask for a lower purchase price.
But sometimes seller concessions may provide a greater immediate benefit.
Depending on the mortgage program and applicable contribution limits, seller funds may potentially be used toward eligible:
-
Closing costs
-
Prepaid expenses
-
Discount points
-
Temporary rate buydowns
Imagine negotiating $10,000 with a seller.
Should that $10,000 reduce the purchase price?
Or could some or all of it be better used toward closing costs or an eligible rate-reduction strategy?
There is no universal answer.
The best option depends on the buyer’s available cash, mortgage program, expected ownership period and monthly-payment priorities.
This is one reason the mortgage strategy should ideally be reviewed before the offer is submitted.
Temporary Rate Buydowns
A temporary buydown can reduce the borrower’s payment during the initial period of the mortgage.
One example is a 1-0 temporary buydown.
The first-year payment is calculated using an effective interest rate one percentage point below the mortgage note rate.
After the temporary period expires, the payment returns to the full note-rate payment.
For example, if the mortgage note rate were 7.25%, the first-year payment under a properly structured 1-0 temporary buydown would be calculated using an effective rate of 6.25%.
That does not mean the borrower has a permanent 6.25% mortgage.
The underlying note rate remains 7.25%.
Temporary buydowns must meet the requirements of the applicable mortgage program, and borrowers generally still need to qualify using the full note-rate payment.
The important question is whether the buyer will comfortably afford the payment once the temporary reduction expires.
What About Paying Points for a Lower Rate?
Another strategy may be a permanent interest-rate buydown.
A borrower pays discount points upfront in exchange for a lower mortgage rate.
Unlike a temporary buydown, the reduced rate generally remains for the life of the mortgage unless the borrower refinances or pays off the loan.
But paying points only makes sense if the savings justify the upfront expense.
Buyers should ask their mortgage professional to calculate the break-even point.
If the cost of the buydown takes five years to recover through monthly savings, but the homeowner expects to refinance or sell in three years, paying those points may not make financial sense.
Compare the Loan Programs
Today's mortgage environment makes it even more important to compare programs rather than automatically selecting one.
Depending on eligibility, Florida buyers may have access to:
Conventional Loans
Some qualified first-time buyers may purchase with as little as 3% down.
FHA Loans
FHA financing may allow a 3.5% down payment and can provide more flexible qualification options for some borrowers.
VA Loans
Eligible veterans, active-duty service members and certain surviving spouses may qualify for 100% financing.
USDA Loans
Eligible buyers purchasing qualifying properties may also have access to 100% financing.
Down-Payment Assistance
Some buyers may qualify for programs designed to reduce the upfront cash required for a purchase.
The best mortgage is not automatically the one advertising the lowest rate.
Compare:
Rate + payment + mortgage insurance + closing costs + cash required + long-term cost.
Adjustable-Rate Mortgages May Enter the Conversation
As fixed rates remain elevated, adjustable-rate mortgages can receive more attention.
An ARM generally provides an initial fixed-rate period before the interest rate becomes eligible for adjustment.
The introductory rate may sometimes be lower than the rate available on a comparable 30-year fixed mortgage.
But buyers need to understand exactly what happens after that initial period.
Important questions include:
-
When can the rate first adjust?
-
How frequently can it change?
-
What are the adjustment caps?
-
What index is used?
-
What is the margin?
-
What is the maximum possible rate?
-
What could the future payment become?
A lower introductory payment should not be evaluated without understanding the potential future payment.
“Buy Now and Refinance Later” Is Not a Complete Strategy
Another phrase buyers hear frequently is:
“Buy now and refinance later.”
Refinancing may absolutely become an option if interest rates fall.
But it should be considered a potential future opportunity—not a guarantee.
A future refinance depends on several factors, including:
-
Available mortgage rates
-
Qualification at that time
-
Credit profile
-
Income
-
Property value
-
Equity
-
Loan guidelines
-
Closing costs
The home purchase should make sense based on the payment the buyer is agreeing to today.
If rates later improve enough to justify refinancing, that can be an additional benefit.
What If Rates Eventually Fall?
Here is the other side of the equation.
Suppose rates eventually fall significantly.
That sounds great for buyers—and it could be.
But lower rates may also bring more buyers back into the market.
That can mean:
-
More competing offers
-
Less seller flexibility
-
Fewer seller concessions
-
Faster-moving inventory
-
Potential upward pressure on home prices
This is why waiting for the lowest possible mortgage rate does not automatically mean receiving the best overall real estate deal.
A higher-rate market may sometimes offer a lower purchase price or better concessions.
A lower-rate market may offer cheaper financing but more competition.
The complete transaction matters.
Fannie Mae Is Not Forecasting a Housing-Market Collapse
Another important part of Fannie Mae’s October forecast is that it does not project a dramatic national collapse in home prices.
The forecast projects its Home Price Index increasing approximately 2.7% in 2026, followed by much slower growth of around 0.6% in 2027.
Fannie Mae also forecasts total home sales of roughly 4.67 million in 2026 and approximately 4.71 million in 2027.
In other words, their current forecast points toward a slower, affordability-constrained market—not necessarily a return to dramatically cheaper home prices.
Of course, Florida markets can behave very differently from national averages.
Real estate is local.
What Florida Buyers Should Do Now
If you are considering purchasing within the next year, focus on what you can actually control.
1. Know Your Comfortable Payment
Determine the monthly housing payment that fits comfortably into your budget.
2. Get Pre-Approved Early
Do not wait until you find the house.
Understanding your mortgage options first allows you to shop with realistic numbers.
3. Compare Multiple Financing Scenarios
Ask to see different:
-
Purchase prices
-
Down payments
-
Loan programs
-
Seller-credit structures
-
Rate-buydown options
4. Review Taxes and Insurance Early
Especially in Florida, these can materially change the monthly payment.
5. Negotiate the Entire Transaction
Price is only one negotiating point.
Seller concessions, repairs and financing strategies may sometimes be equally valuable.
6. Keep Emergency Reserves
Do not automatically use every dollar available toward the purchase.
Owning a home comes with unexpected expenses.
7. Make Sure Today's Payment Works
Do not rely on a future refinance to make an uncomfortable payment affordable.
Should You Buy or Wait?
There is no universal answer.
If purchasing today would stretch the household financially, waiting may absolutely be the responsible decision.
But if the buyer has stable income, adequate reserves, a comfortable payment and finds the right property at favorable terms, a higher mortgage rate alone does not necessarily mean purchasing is a bad decision.
The important thing is to make the decision based on the complete financial picture—not a prediction about where mortgage rates might go next.
The Bottom Line
Mortgage rates remaining above 7% through 2027 would certainly continue creating affordability challenges.
But the answer is not necessarily to sit on the sidelines indefinitely.
Today's buyers may have opportunities to negotiate purchase prices, seller concessions, repairs and mortgage-rate buydowns that were much more difficult to obtain during highly competitive markets.
Instead of trying to perfectly time the mortgage market, focus on four things:
The right house.
The right price.
The right financing.
The right monthly payment.
At Florida Homes & Loans, our real estate and mortgage departments can evaluate those pieces together.
We can look at the property, financing options, estimated payment, seller concessions and cash needed to close before you decide whether the transaction makes sense.
One team. One process. From homes to loans.
Mortgage-rate forecasts are estimates and may change. Rates shown in this article are market averages or forecasts and are not an offer of credit or a quoted rate from Florida Homes & Loans or FHL Mortgages. Actual mortgage rates, pricing, loan programs and qualification requirements vary by borrower and property. Temporary buydowns and seller contributions are subject to applicable loan-program requirements. All loans are subject to credit and property approval. Equal Housing Opportunity. Florida Homes & Loans Inc. | FHL Mortgages | Company NMLS 2295908 | MLO NMLS 2121526.
Categories
Recent Posts