Higher Rates, Better Deals? How Buyers Are Finding Opportunities in Today’s Market
# Higher Rates, Better Deals? How Buyers Are Finding Opportunities in Today’s Market
Mortgage rates above 7% are not exactly what most buyers hoped to see this fall.
They have pushed monthly payments higher, reduced purchasing power and caused some would-be buyers to put their plans on hold.
But there is another side to today’s market that is getting much less attention:
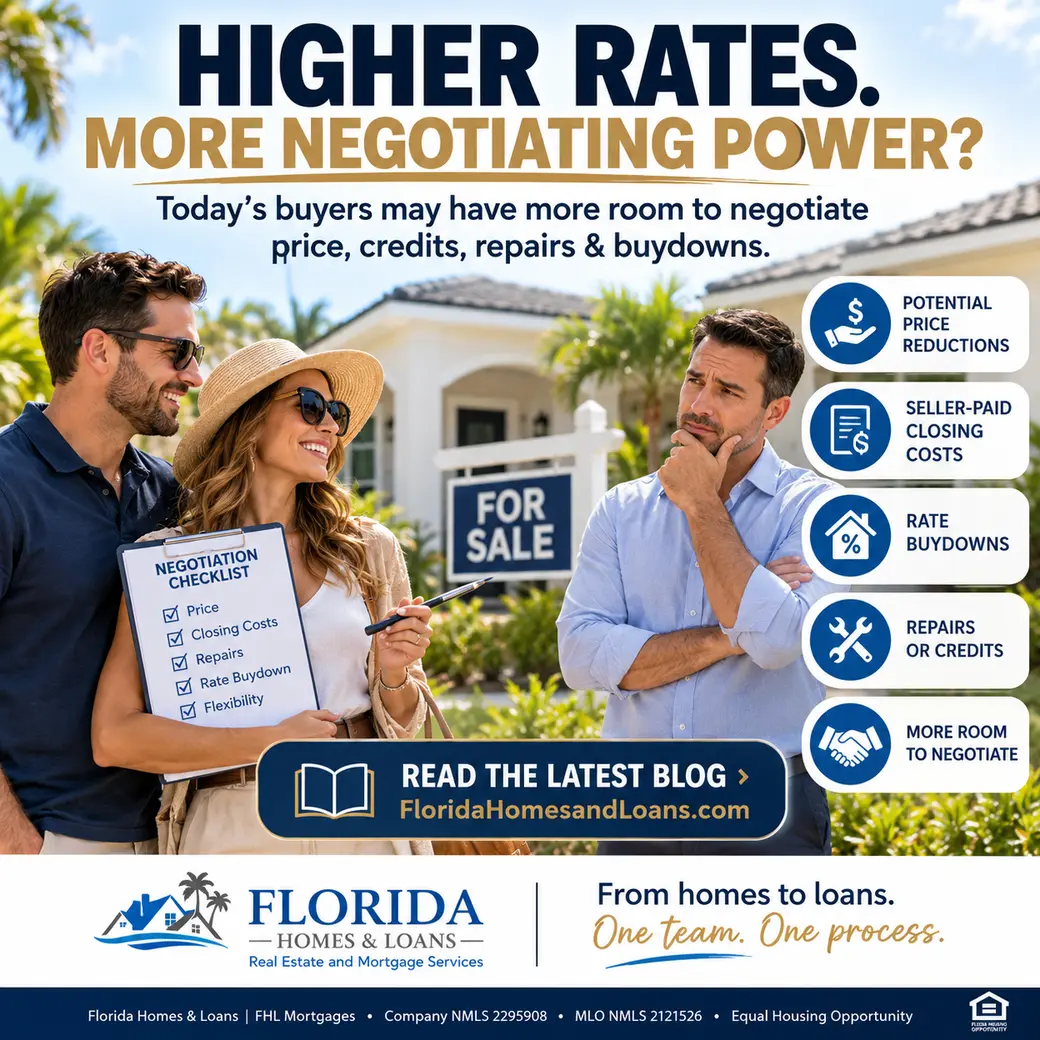
**The buyers who are still shopping may have considerably more negotiating power.**
With fewer buyers competing for homes and more properties sitting on the market, motivated sellers are increasingly willing to discuss price, closing costs, repairs and mortgage-rate buydowns.
That does not suddenly make every home affordable. But it does mean a challenging market can create opportunities for buyers who understand how to negotiate the entire transaction rather than focusing only on the interest rate.
Higher Mortgage Rates Have Changed the Negotiating Table
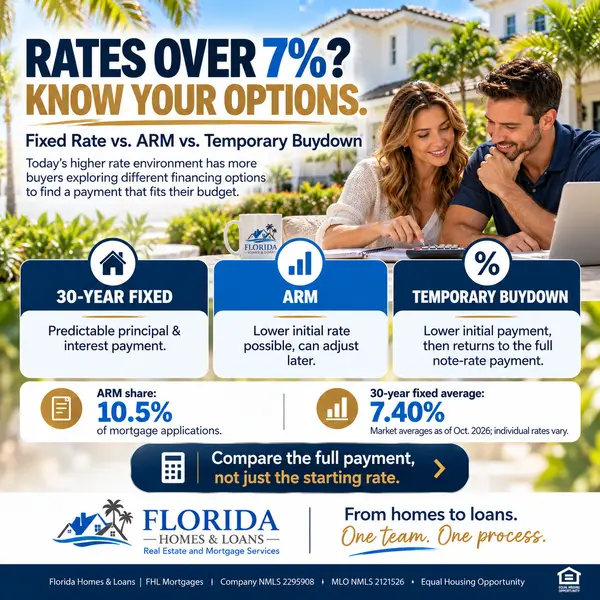
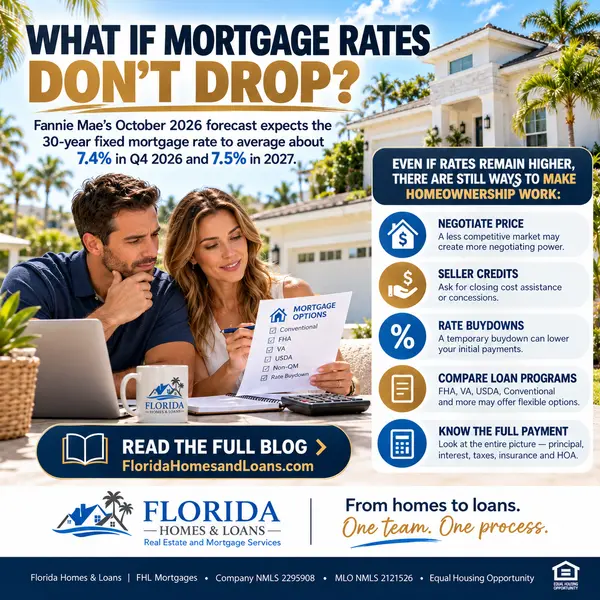
Freddie Mac reported that the average 30-year fixed mortgage rate was 7.40% for the week ending October 15, 2026.
Those borrowing costs have caused many buyers to step away from the market.
At the same time, homes are accumulating on the market in many areas, creating an unusual situation: financing is more expensive, but buyers who remain active may face less competition.
That matters.
A few years ago, buyers in competitive markets were routinely offering above asking price, limiting inspection requests and competing against multiple offers.
Today, the conversation can look very different.
Rather than asking, “How much over asking do we need to offer?” buyers may be able to ask, “What will the seller contribute to make this deal work?”
Seller Concessions Are Becoming Much More Common
Recent Redfin data found that sellers provided concessions in 44.7% of U.S. home sales during the three months ending August 31, 2026.
Those concessions can include money toward repairs, closing costs or mortgage-rate buydowns.
Some buyers are receiving both a negotiated price reduction and additional concessions from the seller.
For buyers who are short on cash at closing or concerned about the monthly payment, the structure of the offer can sometimes be just as important as the purchase price.
What Can Buyers Potentially Negotiate?
Depending on the property, seller motivation, loan program and local market conditions, buyers may be able to negotiate:
- A lower purchase price
- Seller-paid closing costs
- Funds toward a temporary or permanent rate buydown
- Repairs or repair credits
- Assistance with certain prepaid expenses
- Home warranties
- Closing-date flexibility
- Credits related to inspection findings
The important part is deciding which concession actually helps that particular buyer the most.
A $10,000 price reduction sounds attractive, but another structure could potentially provide more immediate benefit if the buyer is struggling with cash to close or the first-year monthly payment.
That is why the real estate agent and mortgage professional should be looking at the offer together.
Sometimes a Seller Credit Can Be More Valuable Than a Small Price Reduction
Consider a buyer deciding between asking the seller to reduce the purchase price or provide a closing-cost credit.
A modest price reduction may only change the monthly principal-and-interest payment by a relatively small amount.
A seller credit, when permitted by the loan program and transaction, could instead reduce the buyer’s cash needed at closing or help fund an eligible mortgage-rate buydown.
The better choice depends on the numbers.
Rather than automatically asking for a certain percentage off the asking price, buyers should have their mortgage professional model different scenarios before the offer is written.
Rate Buydowns Are Back in the Conversation
One strategy appearing more frequently is a mortgage-rate buydown.
With a temporary buydown, funds contributed at closing are used to temporarily reduce the payment during the beginning of the loan.
For example, a 1-0 temporary buydown generally provides a payment based on an effective interest rate 1 percentage point below the note rate during the first year before returning to the full note-rate payment afterward.
The borrower must generally qualify based on the full note rate, and the structure must meet the requirements of the applicable mortgage program.
A buydown is not automatically the best choice for every buyer. But when a seller is willing to contribute money toward the transaction, it is one option worth comparing.
Do Not Buy Based on the Hope of Refinancing Later
You may hear buyers say:
“I’ll just buy now and refinance when rates come down.”
Refinancing may be possible later, but it should never be treated as guaranteed.
Future rates are unknown. The borrower will also need to qualify for the refinance at that time, the property must meet applicable requirements, and refinancing normally comes with closing costs.
The purchase should make financial sense based on the payment the buyer is agreeing to today.
If rates improve later and refinancing makes sense, that can be an added benefit—not the reason the buyer stretches beyond a comfortable budget now.
Florida Buyers May Have an Interesting Window
Fall traditionally brings fewer buyers into the market, and this year that seasonal slowdown is combining with higher mortgage rates.
Florida Realtors recently highlighted that buyers in several large Florida markets may see more choices, less competition and greater negotiating room during late fall.
That does not mean every seller will accept a low offer.
Well-priced, desirable homes can still attract competition.
However, properties that have been sitting on the market, experienced price reductions, require repairs or have sellers with a strong reason to move may create negotiating opportunities.
Days on Market Can Tell a Story
A home that was listed yesterday is very different from one that has been available for 60, 90 or 120 days.
Longer market time does not automatically mean something is wrong with the property.
Sometimes the home simply started at an unrealistic price.
Other times the seller may have purchased another property, relocated, inherited the home or simply reached the point where they are ready to negotiate.
This is where a good buyer strategy matters.
Instead of looking only at newly listed properties, buyers should also review homes that have accumulated market time, experienced price adjustments or returned to the market after a previous contract fell through.
## Inspections Matter Again
More negotiating power can also mean buyers do not have to accept every problem with a property simply to win the house.
A professional inspection may identify roof concerns, plumbing issues, electrical problems, HVAC deficiencies or other items that affect the cost of owning the home.
In a slower market, sellers may be more willing to make repairs, offer a credit or adjust the purchase price.
That can make a significant difference—particularly in Florida, where roof condition, electrical systems and other property characteristics can also affect homeowners insurance.
Sellers Need a Different Strategy Too
The shift in negotiating power affects sellers just as much as buyers.
Homes that are priced based on what a neighbor sold for during a hotter market may struggle if current buyers cannot support the payment.
Today’s sellers should pay close attention to competing inventory, days on market, price reductions and the condition of nearby homes.
A strong offer may also include a request for concessions.
Rejecting every request automatically can sometimes mean losing a qualified buyer and starting the marketing process again.
The objective is not necessarily to “win” every individual negotiation point.
It is to structure a transaction that makes financial sense for both sides and reaches the closing table.
The Lowest Rate Is Not the Only Way to Get a Better Deal
Mortgage rates are important—but they are only one part of the transaction.
A buyer may potentially improve the overall deal through the purchase price, seller concessions, repairs, financing structure and cash needed to close.
That is why waiting exclusively for rates to fall can be complicated.
If rates eventually decline substantially, more buyers may return to the market. Increased demand can reduce negotiating leverage and create stronger competition for desirable homes.
No one knows exactly where rates or home prices will go next.
What buyers can evaluate is the opportunity available today.
The Bottom Line
Today’s market is challenging, but challenging does not mean impossible.
Higher rates have caused many buyers to step back. For the buyers who remain financially prepared, that slowdown can create an opportunity to negotiate in ways that were extremely difficult during the hottest years of the housing market.
The right property at the right price—with the right financing and concessions—can sometimes make more sense than simply waiting for a headline mortgage rate.
Before writing an offer, buyers should understand:
their comfortable monthly payment, estimated taxes and insurance, total cash needed to close, available loan programs and which seller concessions would provide the greatest benefit.
At Florida Homes & Loans, our real estate and mortgage teams can look at those pieces together.
Instead of finding the house first and figuring out the financing afterward, we can evaluate the property, offer strategy and mortgage options as one complete picture.
**One team. One process. From homes to loans.**
*This article is provided for general educational purposes only and is not a commitment to lend, financial advice or a guarantee that a seller will provide concessions. Mortgage rates, loan programs, seller-contribution limits and qualification requirements vary. Temporary buydowns are subject to program requirements, and borrowers may be required to qualify at the full note rate. All financing is subject to credit and property approval. Equal Housing Opportunity. Florida Homes & Loans Inc. | FHL Mortgages | Company NMLS 2295908 | MLO NMLS 2121526.*
**Sources:** Homes.com News, Freddie Mac Primary Mortgage Market Survey, Redfin housing-market research and Florida Realtors.
Categories
Recent Posts