Do Homes Lose Value as They Age? Why Older Homes Can Still Be Worth More
Do Homes Lose Value as They Age? Why Older Homes Can Still Be Worth More
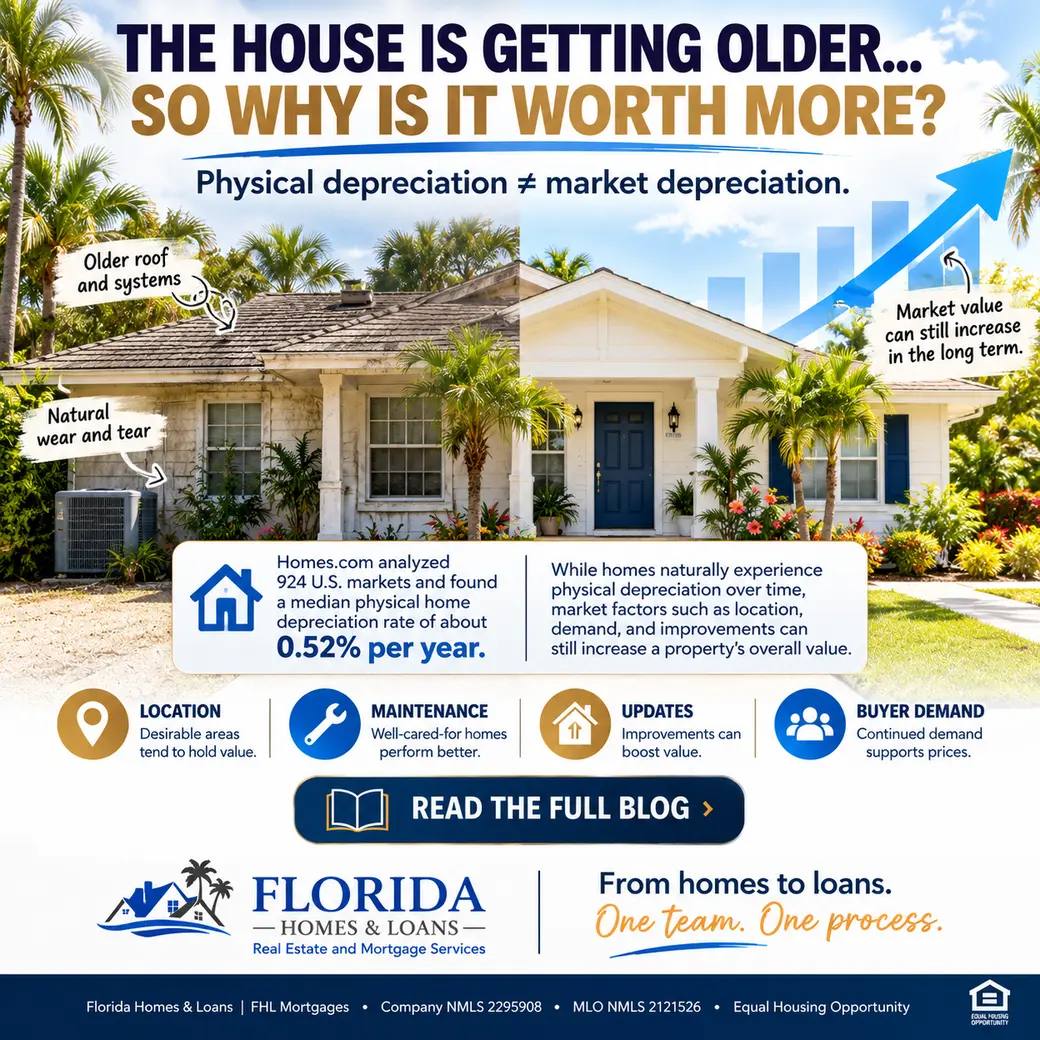
If your house gets one year older every year, shouldn’t it eventually become worth less?
It sounds logical. The roof ages, the HVAC works through another Florida summer, plumbing and electrical systems get older, and eventually even the trendiest kitchen starts looking a little dated.
Yet many homeowners have watched the value of their property increase substantially while the actual house continues to age.
How can both things be true?
Because the physical house and the market value of the property are not the same thing.
A home can experience physical depreciation while the overall property continues to appreciate because its value is also influenced by location, land, buyer demand, housing supply, improvements and the surrounding community.
For Florida homeowners and buyers, understanding that difference is especially important.
A House Is More Than the Structure
When you buy a home, you are not simply purchasing drywall, cabinets, plumbing and a roof.
You are also purchasing the land and everything associated with its location.
That could include proximity to:
-
Beaches and waterways
-
Major employers
-
Schools
-
Shopping and restaurants
-
Downtown areas
-
Transportation
-
Recreation
-
Desirable neighborhoods
There is only so much land in the places people most want to live.
That means an older house in a highly desirable location can sometimes be worth considerably more than a newer home somewhere buyers find less desirable.
The physical structure may be aging while the land underneath it becomes increasingly valuable.
Florida Homes Have Their Own Aging Challenges
Florida homes experience conditions that properties in many other parts of the country do not face to the same degree.
Our homes regularly deal with:
Heat. Humidity. Heavy rain. Strong UV exposure. Tropical weather. Salt air in coastal areas.
Those conditions can take a toll on building materials.
Roofs, exterior paint, caulking, HVAC equipment, windows, doors and other components all require maintenance.
For coastal homeowners, salt exposure can also accelerate corrosion on certain materials and equipment.
So when evaluating a Florida property, the year it was built is useful—but it does not tell the complete story.
Which Home Is Really “Older”?
Imagine two Florida homes.
One was built in 1985.
Since then, the owners have replaced the roof, HVAC system, electrical panel, plumbing, windows and water heater.
The kitchen and bathrooms have also been updated.
The second home was built in 2005—but much of the property is still original.
Technically, the first house is 20 years older.
But when you look at the major systems and the expenses a new homeowner may face over the next several years, the older property could actually be in better condition.
That is why buyers should ask:
“What has been replaced and maintained?”
Not simply:
“What year was it built?”
Maintenance Can Make a Huge Difference
Two houses built by the same builder in the same year can age very differently.
One homeowner might consistently maintain the property.
They replace worn components before they fail, service the HVAC, repair leaks quickly, maintain exterior seals and keep moisture under control.
The homeowner next door may postpone repairs for years.
Eventually, deferred maintenance begins adding up.
The houses may be the same age on paper, but their condition—and potentially their marketability—can be completely different.
For sellers, maintenance records can therefore become surprisingly valuable.
Keeping receipts, permits, warranties and documentation for major improvements can help buyers understand exactly what has been done to the property.
In Florida, Pay Particular Attention to the Roof
The roof is one of the biggest considerations when purchasing an older Florida home.
It can affect:
-
Future repair expenses
-
Homeowners insurance
-
Wind-mitigation results
-
Buyer confidence
-
Mortgage qualification in certain circumstances
-
Resale value
A home with a well-maintained or recently replaced roof may have a major advantage over a similarly priced property with a roof approaching the end of its useful life.
The same idea applies to HVAC, plumbing, electrical systems and windows.
Older Doesn't Automatically Mean Worse
There are plenty of reasons buyers specifically seek older homes.
Older Florida neighborhoods may offer things that are difficult to find in newer developments:
🌴 Larger lots
🌳 Mature trees
🏡 Established neighborhoods
🚤 Waterfront access
🚫 Fewer community restrictions in some areas
📍 Locations closer to established downtowns and beaches
🏠 Architectural character
🚗 Larger driveways or more flexible parking
A newer home might have modern finishes and energy-efficient systems.
An older property might have a larger lot, better location and several major systems already replaced.
Neither is automatically better.
The correct choice depends on the property, the condition and the buyer's priorities.
Cosmetic Age and Functional Age Are Different
This is another important distinction.
A kitchen with brown cabinets and older countertops might look dated—but it may function perfectly.
That is very different from:
-
An aging roof
-
Active plumbing leaks
-
Electrical concerns
-
Moisture intrusion
-
Structural problems
-
An HVAC system nearing failure
Buyers should learn to separate cosmetic projects from major ownership expenses.
Paint can be changed.
Cabinet hardware can be replaced.
Flooring can be updated.
A major roof or plumbing replacement requires a very different budget.
Buyers: Investigate the Effective Age of the Home
When considering an older property, look beyond the number on the tax record.
Ask about:
-
Roof — When was it installed and what is its condition?
-
HVAC — How old is the system and has it been regularly serviced?
-
Plumbing — Have supply or drain lines been replaced? Have there been previous leaks?
-
Electrical — Has the panel or wiring been updated?
-
Windows and doors — Are they original, updated or impact-rated?
-
Water heater — How old is it?
-
Renovations — Were major improvements properly permitted when required?
-
Moisture history — Have there been roof leaks, plumbing leaks or water intrusion?
A professional home inspection can help buyers evaluate the condition of those systems.
Sellers: Your Maintenance History Can Help Tell the Story
If you are selling an older property, organize your documentation before listing.
Records for major improvements can include:
-
Roof replacement
-
HVAC installation
-
Plumbing improvements
-
Electrical work
-
Windows and doors
-
Water heater
-
Remodels and additions
-
Wind-mitigation inspections
-
Termite treatment
-
Major appliances
Instead of allowing buyers to see only “Built in 1987,” you can help them see:
Built in 1987—but roof, HVAC, plumbing and windows have all been updated.
That creates a completely different conversation.
Renovations Don't Automatically Equal Profit
Homeowners should also be careful about assuming every renovation will increase their home value dollar-for-dollar.
A $50,000 remodel does not automatically add $50,000 to the market value.
The value of an improvement depends on:
-
The neighborhood
-
Buyer expectations
-
Current market conditions
-
The quality of the work
-
The type of renovation
-
Comparable home sales
Before spending significant money preparing a property for sale, it can be helpful to determine which improvements buyers in that particular market actually care about.
Sometimes correcting maintenance and insurance-related concerns produces a better result than completing an expensive cosmetic renovation.
Why Can an Older Home Keep Increasing in Value?
Because market value is influenced by several forces working together.
Think of it this way:
Physical age pushes one direction.
But:
Location + land + demand + limited housing supply + improvements + market conditions can push the other direction.
If those positive market forces outweigh physical depreciation, the overall property value can continue rising.
That is why comparing a house directly with something like a vehicle can be misleading.
A car is primarily the depreciating object itself.
Real estate includes both the physical structure and the land/location attached to it.
The Lowest-Priced Home Isn't Always the Least Expensive
This is especially important for buyers.
Imagine two properties:
Home A: $350,000 with an aging roof, older HVAC and several upcoming repairs.
Home B: $365,000 with a newer roof, updated HVAC and updated major systems.
Home A has the lower purchase price.
But that does not automatically make it the less expensive home to own.
Insurance, repairs, maintenance and replacement costs all need to be considered alongside the mortgage payment.
This is why we encourage buyers to look at the complete cost of homeownership, not simply the asking price.
The Bottom Line
Yes, houses physically age.
Roofs wear out.
Air conditioners eventually need replacing.
Materials deteriorate and styles become dated.
But that does not mean the entire property automatically loses value every year.
A well-maintained older Florida home in a desirable location can continue appreciating even while some of its physical components depreciate.
For buyers, don't dismiss a property simply because of its age.
Look at its condition, updates, location and complete ownership cost.
For sellers, maintaining your home and documenting improvements can help buyers understand what they're actually purchasing.
And for homeowners who are wondering whether their aging house can still be a valuable asset?
The answer may very well be yes.
Florida Homes & Loans helps buyers and sellers look at the entire picture—from property condition and market value to financing and the complete cost of owning the home.
One team. One process. From homes to loans.
This article is provided for general educational purposes only and is not legal, appraisal, tax, insurance, investment or financial advice. Property values, maintenance costs, insurance requirements and financing eligibility vary by property and market. Past appreciation does not guarantee future value increases. Equal Housing Opportunity. Florida Homes & Loans Inc. | FHL Mortgages | Company NMLS 2295908 | MLO NMLS 2121526.
Categories
Recent Posts