Should You Buy a Condo or a Single-Family Home in Florida?
Should You Buy a Condo or a Single-Family Home in Florida?
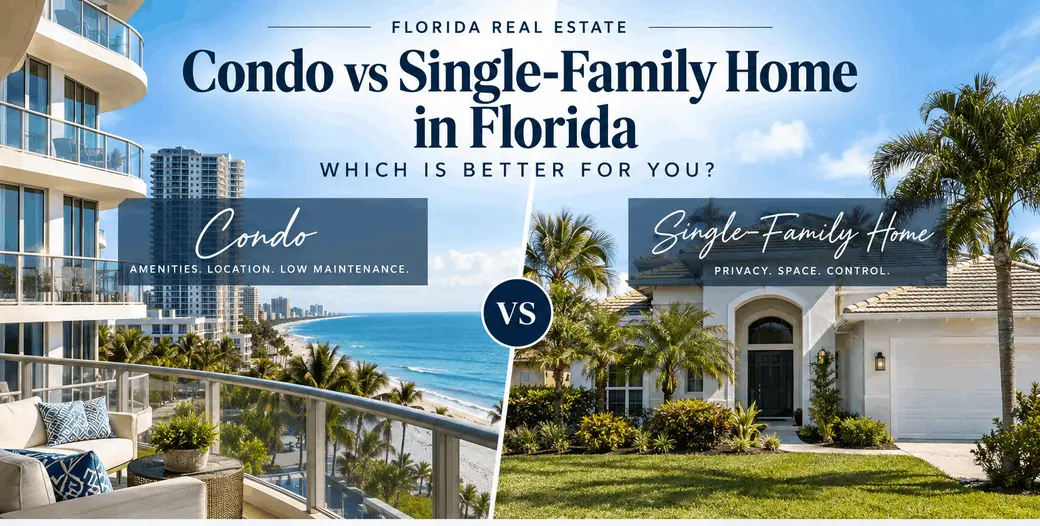
A condo can offer lower-maintenance living, amenities and access to locations where a single-family home may cost considerably more. A single-family home usually gives you more privacy and control over the property. In Florida, however, the better choice also depends on association finances, insurance, special assessments, financing and the long-term cost of ownership.
The short answer: A condo may make sense if you value lower exterior maintenance, amenities and location. A single-family home may be a better fit if you want more privacy, land and control over future property expenses. In Florida, buyers should compare the total monthly cost and financial health of the condominium association—not simply the purchase price.
Florida buyers often find themselves comparing a condo with a single-family home in the same general price range.
At first glance, the condo may appear significantly less expensive. But once you add monthly condominium fees, possible special assessments, insurance, reserves and financing considerations, the comparison can look very different.
The goal should not simply be to decide which property costs less today. It should be to understand what you are actually buying and what responsibilities come with each option.
A Condo May Appeal to You If...
- You prefer less exterior maintenance.
- You want amenities such as a pool, gym or clubhouse.
- You want to be closer to the beach, downtown or other higher-cost locations.
- You do not need a large yard.
- You are comfortable living under association rules.
A Single-Family Home May Appeal to You If...
- You want more privacy and outdoor space.
- You want greater control over your property.
- You prefer not to share major building expenses with other owners.
- You want flexibility for pets, parking, renovations or outdoor improvements.
- You want to avoid condominium-specific financing requirements.
Do Not Compare Purchase Price Alone
One of the biggest mistakes buyers can make is comparing a $300,000 condo with a $375,000 house and automatically assuming the condo will be significantly cheaper every month.
A condo may have a monthly association fee that covers items such as exterior maintenance, building insurance, landscaping, amenities, water, cable, reserves or other shared expenses.
A single-family homeowner may pay many of those expenses independently instead.
That means the real comparison should include the mortgage payment, property taxes, insurance, HOA or condominium fees and any other recurring property expenses.
What Does a Florida Condo Fee Actually Cover?
There is no universal answer. Every condominium association is different.
Depending on the community, the fee may contribute toward the building's master insurance policy, common-area maintenance, landscaping, elevators, pools, security, exterior repairs, water, cable, reserves and management expenses.
Buyers should review exactly what is included rather than simply deciding whether the monthly fee looks high or low.
A very low condo fee is not automatically a good thing.
If an association has historically collected too little money for reserves or deferred major maintenance, owners may eventually face increased fees or special assessments.
Why Florida Condo Reserves Matter More Than Ever
Florida has strengthened inspection and reserve requirements for certain condominium buildings.
Depending on the building's height, age and circumstances, buyers may encounter documents relating to milestone inspections, Structural Integrity Reserve Studies, reserve funding and planned repairs.
These documents can be extremely important because they may identify future building expenses and how the association plans to pay for them.
When reviewing an older or multi-story condominium, buyers should pay particular attention to the association's reserves, recent engineering reports, planned repairs and any existing or proposed special assessments.
What Is a Condo Special Assessment?
A special assessment is an additional amount owners may be required to pay when the association needs money beyond its normal operating budget or available reserves.
For example, an association may need funds for major structural work, roofing, concrete restoration, elevators, balconies, exterior waterproofing or another large project.
Depending on the amount, an assessment may be due as a lump sum or collected through installments.
Before purchasing a condo, buyers should ask about current assessments, recently completed assessments and discussions about possible future projects.
Is Financing a Condo Harder Than Financing a House?
It can be.
When financing a single-family home, the lender primarily evaluates the borrower and the property.
With many condominiums, the lender may also need to review the condominium project itself.
Depending on the loan program and project, the review may consider matters such as the association's finances, insurance, litigation, special assessments, project completion and other eligibility requirements.
This means a buyer may personally qualify for the mortgage while a particular condominium project creates additional financing issues.
Before becoming emotionally attached to a condo, verify the financing early.
Your lender should know that you are considering a condominium so the project requirements can be reviewed as early as possible.
How Is Insurance Different?
With a single-family home, the homeowner generally carries insurance covering the structure and personal property, subject to the terms and exclusions of the policy.
A condominium association normally has a master insurance policy covering certain portions of the building and common elements, while the individual owner typically carries a separate condo-unit policy for items that are the owner's responsibility.
Exactly where the association's responsibility ends and the unit owner's begins can vary.
Florida buyers should have an insurance professional review the property and association documents rather than assuming that the condo fee eliminates the need for individual insurance.
What About Maintenance?
This is where condos can be very attractive.
In many communities, owners are not individually responsible for mowing lawns, maintaining the exterior of the building, repairing common roofs or maintaining shared amenities.
For a seasonal Florida resident, retiree or buyer who does not want extensive exterior maintenance, that can be valuable.
A single-family home puts more responsibility directly on the homeowner, but it also gives the homeowner more control over when and how work is completed.
How Much Control Do You Want?
Condominium living generally means accepting more community rules.
Depending on the association, rules may cover pets, vehicles, parking, rentals, renovations, flooring, balconies, exterior decorations and other aspects of the property.
A single-family home may still have an HOA, so buying a house does not automatically mean there are no restrictions.
The important thing is to review the governing documents before purchasing and make sure the community's rules work with how you actually intend to use the property.
What Should Florida Buyers Look at Before Buying a Condo?
In addition to the normal property inspection and purchase contract, a condo buyer should understand the association itself.
That includes reviewing the association budget, current fees, reserves, insurance information, recent meeting minutes, pending or approved assessments and applicable inspection or reserve-study documentation.
For coastal properties, buyers should also understand flood exposure, wind-related considerations and the age and condition of the building.
Condo vs Single-Family Home: Quick Comparison
| Consideration | Condo | Single-Family Home |
|---|---|---|
| Exterior Maintenance | Often handled by the association. | Usually homeowner responsibility. |
| Monthly Fees | Condo fees can be significant. | May have an HOA, but often lower than full condo fees. |
| Privacy | Usually more shared walls and common areas. | Generally more privacy. |
| Amenities | Often includes shared amenities. | Depends on the community. |
| Financing | Borrower, unit and project may need to qualify. | Generally no condominium-project review. |
| Major Building Expenses | Shared through the association and potentially assessments. | Homeowner generally controls and pays directly. |
| Property Control | Usually more association restrictions. | Typically greater control, subject to HOA/local rules. |
So, Which One Should You Buy?
There is no universal answer.
A well-managed Florida condo with healthy reserves, reasonable fees and amenities you will actually use can make excellent sense for the right buyer.
A single-family home may be more appropriate if you want privacy, outdoor space, greater control and fewer shared financial decisions.
The key is comparing the complete financial picture and not assuming that a condo is cheaper simply because its purchase price is lower.
Frequently Asked Questions
Are condos cheaper than houses in Florida?
Condos often have lower purchase prices than comparable single-family homes in the same location, but the total monthly cost can be affected by condominium fees, insurance and assessments.
Can a Florida condo have a special assessment?
Yes. Condominium owners may be assessed additional amounts when the association needs money for expenses that are not sufficiently covered by its normal budget or available reserves.
Do Florida condos require inspections?
Certain Florida condominium buildings are subject to milestone inspection and structural reserve requirements based on factors including building height, age and applicable law.
Is it harder to get a mortgage on a condo?
It can be. In addition to qualifying the borrower and unit, some mortgage programs require the condominium project itself to meet specific eligibility standards.
Does the condo association's insurance cover my unit?
Not necessarily. The association's master policy and the unit owner's policy generally cover different responsibilities. Buyers should review both the condominium documents and insurance coverage with an insurance professional.
Is a condo good for a second home in Florida?
It can be, particularly for buyers who value lower exterior maintenance and shared amenities. Buyers should still review rental restrictions, association finances, insurance and financing requirements.
What should I review before buying a Florida condo?
Important items can include the condominium documents, budget, reserves, insurance, meeting minutes, current or proposed assessments and any applicable milestone inspection or Structural Integrity Reserve Study documentation.
Can a single-family home still have an HOA?
Yes. Many Florida single-family communities have homeowners associations with their own fees, rules and restrictions.
Comparing Florida Condos and Single-Family Homes?
Florida Homes & Loans can help you compare more than the listing price. We can help you look at the property, community expenses, association considerations and financing so you understand the full picture before making an offer.
This information is provided for general educational purposes and is not legal, insurance, tax or financial advice. Condominium requirements, association documents, insurance coverage, lending guidelines and property conditions vary. Buyers should review the specific property and condominium association with the appropriate licensed professionals before making a purchase decision. Loan programs and eligibility requirements are subject to change and borrower and property qualification.
Categories
Recent Posts