Is an FHA Loan or Conventional Loan Better for a Florida Buyer?
Is an FHA Loan or Conventional Loan Better for a Florida Buyer?
Neither FHA nor conventional financing is automatically better for every Florida buyer. FHA loans can be a strong option for buyers with smaller down payments, certain credit profiles or higher debt-to-income ratios, while conventional financing may offer advantages for buyers with stronger credit, lower mortgage-insurance costs or specific long-term goals.
May Be Better When...
- Your credit profile makes conventional pricing expensive
- You want a smaller minimum down payment
- Your debt-to-income ratio needs more flexibility
- You need more flexible underwriting
- The property will be your primary residence
May Be Better When...
- You have stronger credit
- You want potentially lower mortgage-insurance costs
- You want more property or occupancy options
- You plan to put more money down
- You want mortgage insurance that may be removable later
What Is an FHA Loan?
An FHA loan is a mortgage made by an approved lender and insured by the Federal Housing Administration.
FHA financing is designed to provide broader access to homeownership and is commonly used by buyers who may not receive the best terms through conventional financing.
FHA financing may appeal to buyers looking for:
- A relatively low down-payment requirement
- More flexible credit guidelines
- Competitive mortgage pricing
- Primary-residence financing
- More flexibility with certain debt-to-income scenarios
FHA loans are not only for first-time home buyers.
A buyer who has owned a home previously may still potentially use FHA financing as long as the borrower, property and transaction meet applicable program requirements.
What Is a Conventional Loan?
A conventional mortgage is a home loan that is not insured by FHA, VA or USDA.
Many conventional mortgages follow guidelines established by Fannie Mae or Freddie Mac.
Depending on the transaction, conventional financing may offer:
- Low-down-payment options
- Private mortgage insurance rather than FHA mortgage insurance
- Primary-residence financing
- Second-home financing
- Investment-property financing
- Different property eligibility options
Conventional financing is not limited to buyers putting 20% down.
Do You Need 20% Down for a Conventional Loan?
No.
This is one of the most common misconceptions we hear from home buyers.
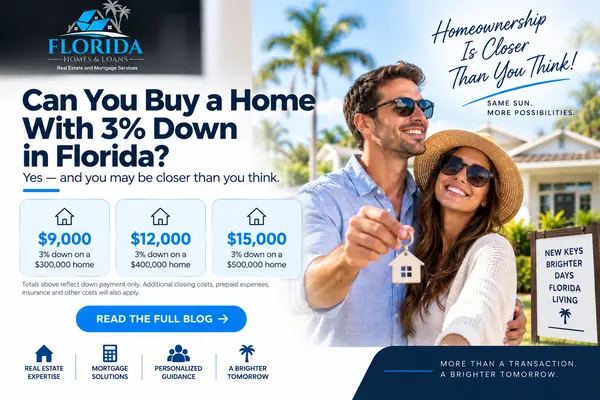
Certain eligible conventional mortgage programs can allow qualified buyers to purchase a primary residence with as little as 3% down.
On a $400,000 home, a 3% down payment would equal $12,000. That does not mean the buyer's total cash to close is only $12,000, because closing costs, prepaid expenses and escrow deposits may also apply.
Other buyers may choose 5%, 10%, 15% or 20% down depending on available funds, mortgage pricing and financial goals.
How Much Down Does FHA Require?
FHA financing can allow an eligible borrower to purchase with a minimum investment as low as 3.5% when applicable FHA credit requirements are satisfied.
Borrowers with certain lower credit scores may face higher minimum investment requirements or may not meet a particular lender's requirements.
It is also important to distinguish between the down payment and the total amount needed at closing.
A buyer may also need funds for:
- Closing costs
- Prepaid interest
- Homeowners insurance
- Property-tax escrows
- Insurance escrows
- Appraisal
- Inspections
- Other applicable transaction expenses
Which Loan Is Better If Your Credit Score Is Lower?
FHA financing may sometimes be more competitive for borrowers with lower credit scores.
Conventional mortgage pricing can be more sensitive to credit score and loan-to-value ratio.
However, this does not mean every borrower with less-than-perfect credit should automatically choose FHA.
The correct comparison should include:
- Interest rate
- Mortgage insurance
- Upfront mortgage costs
- Monthly payment
- Cash to close
- Long-term mortgage cost
Sometimes the conventional option is still better. Sometimes FHA wins clearly.
What Is the Difference Between FHA Mortgage Insurance and Conventional PMI?
Mortgage insurance is one of the biggest differences between FHA and conventional financing.
FHA loans typically include both an upfront mortgage-insurance premium and an annual mortgage-insurance premium paid through the monthly mortgage payment.
Conventional loans with less than 20% down commonly require private mortgage insurance, or PMI.
Conventional PMI can vary based on factors such as:
- Credit score
- Down payment
- Loan-to-value ratio
- Occupancy
- Mortgage structure
For a borrower with strong credit, conventional PMI may sometimes be significantly less expensive than FHA mortgage insurance.
Can Mortgage Insurance Be Removed Later?
This can be an important long-term consideration.
Conventional private mortgage insurance may potentially be canceled or terminate once applicable equity, payment-history and legal requirements are satisfied.
FHA mortgage insurance works differently.
Depending on the original loan-to-value ratio and FHA requirements applicable to the loan, FHA annual mortgage insurance may remain for many years or potentially for the life of the mortgage unless the borrower later refinances into another loan.
Buyers planning to keep the same mortgage for a long period should consider this when comparing programs.
Which Loan Is Better for a First-Time Home Buyer?
Either one can be.
FHA is often associated with first-time buyers because of its smaller down-payment requirement and flexible underwriting.
But eligible first-time buyers may also have access to conventional programs requiring relatively small down payments.
A first-time buyer should therefore avoid assuming that FHA is automatically the default choice.
Run both scenarios whenever possible.
Is FHA Only for First-Time Buyers?
No.
FHA does not generally require a borrower to be purchasing their first home.
A previous homeowner may still potentially qualify for FHA financing if the borrower meets applicable requirements.
FHA does, however, generally focus on primary-residence financing rather than vacation homes or investment properties.
Are FHA Appraisals Harder Than Conventional Appraisals?
FHA appraisals include property-condition considerations in addition to establishing value.
FHA-financed properties generally need to meet applicable standards relating to safety, security and structural soundness.
That does not mean an older home automatically cannot be purchased with FHA financing.
However, significant issues such as certain health or safety concerns may need to be corrected before closing.
Buyers purchasing older Florida homes should consider property condition early—particularly when there are concerns involving:
- Roof condition
- Electrical systems
- Water intrusion
- Structural issues
- Missing safety components
- Other material property defects
Which Loan Is Better for a Florida Condo?
This depends on both the buyer and the condominium project.
Condo financing can involve additional project-level requirements.
The lender may review factors such as:
- Association insurance
- Reserves
- Special assessments
- Litigation
- Structural issues
- Owner occupancy
- Commercial space
- Other project characteristics
FHA and conventional programs have different condominium eligibility requirements.
Before making an offer on a Florida condo, it is helpful to evaluate the project—not simply whether the buyer qualifies personally.
Can the Seller Pay Closing Costs With FHA or Conventional Financing?
Potentially.
Both FHA and conventional mortgage programs can permit eligible seller contributions toward certain buyer closing costs.
The permitted amount depends on the applicable program and transaction structure.
Seller concessions can potentially be used strategically to reduce:
- Buyer cash to close
- Certain eligible lender costs
- Eligible prepaid expenses
- Eligible discount-point costs
- Other allowable closing expenses
This can be particularly important when deciding between two mortgage options with different upfront costs.
Which Loan Has the Lower Interest Rate?
There is no universal answer.
FHA mortgage rates can sometimes appear lower than conventional rates, particularly for certain credit profiles.
But the interest rate alone does not tell you which mortgage is cheaper.
You also need to compare:
- Mortgage insurance
- Upfront mortgage premiums
- Discount points
- Lender fees
- Monthly payment
- Total cash to close
A lower advertised interest rate can still produce a more expensive overall mortgage.
When Might FHA Be the Better Choice?
FHA may be worth considering when:
- Credit challenges make conventional financing expensive
- The buyer needs more flexible underwriting
- The buyer wants a relatively small down payment
- The property will be a primary residence
- The FHA payment and cash-to-close structure is more favorable
When Might Conventional Financing Be Better?
Conventional financing may be worth considering when:
- The buyer has stronger credit
- Conventional mortgage insurance is inexpensive
- The buyer wants more occupancy options
- The buyer plans to keep the mortgage long term
- Mortgage-insurance cancellation is important
- The conventional payment or total cost is lower
Why You Should Compare Both Before Choosing
Buyers sometimes become focused on the name of the mortgage program rather than the actual numbers.
Instead, compare the complete transaction.
- Purchase price
- Down payment
- Loan amount
- Interest rate
- Principal and interest
- Mortgage insurance
- Estimated taxes and insurance
- Total monthly housing payment
- Estimated cash to close
- Long-term mortgage-insurance considerations
Once those numbers are side by side, the better option often becomes much clearer.
Frequently Asked Questions
No. FHA financing is not limited to first-time home buyers. Previous homeowners may potentially qualify when the borrower, property and transaction meet applicable FHA requirements.
Certain eligible conventional mortgage programs can allow qualified borrowers to purchase a qualifying primary residence with as little as 3% down. Program requirements apply.
Eligible FHA borrowers may be able to purchase with a minimum investment as low as 3.5%. Credit and other program requirements apply, and total cash to close will usually include more than the down payment alone.
It can be. FHA may offer more favorable qualification or pricing for certain credit profiles, but buyers should still compare FHA and conventional scenarios before deciding.
No. Conventional private mortgage insurance is commonly required when the loan exceeds certain loan-to-value levels, but borrowers with sufficient equity may not require monthly PMI.
FHA mortgage-insurance duration depends on the loan structure and applicable FHA requirements. Some borrowers may need to refinance into another mortgage later if eliminating FHA mortgage insurance becomes a financial priority.
Neither is universally better. The best choice depends on your credit, income, debt, down payment, property, mortgage insurance, interest rate, cash to close and long-term plans.
Do Not Choose FHA or Conventional Until You Compare Both
At Florida Homes & Loans, we can compare FHA and conventional financing side by side so you can see the actual difference in down payment, mortgage insurance, monthly payment and estimated cash needed to close.
Because we handle both real estate and mortgage services, we can also look at the property, seller concessions and financing strategy together before you make an offer.
This article is for general educational purposes only and is not financial, tax or legal advice. FHA and conventional mortgage requirements, minimum investments, mortgage-insurance requirements, rates, pricing and underwriting guidelines are subject to change. Not every borrower or property will qualify for every program. This is not a commitment to lend. All financing is subject to borrower, credit, income, property and underwriting approval. Equal Housing Opportunity.
Categories
Recent Posts