Can Self-Employed Buyers Get a Mortgage in Florida?
Can Self-Employed Buyers Get a Mortgage in Florida?
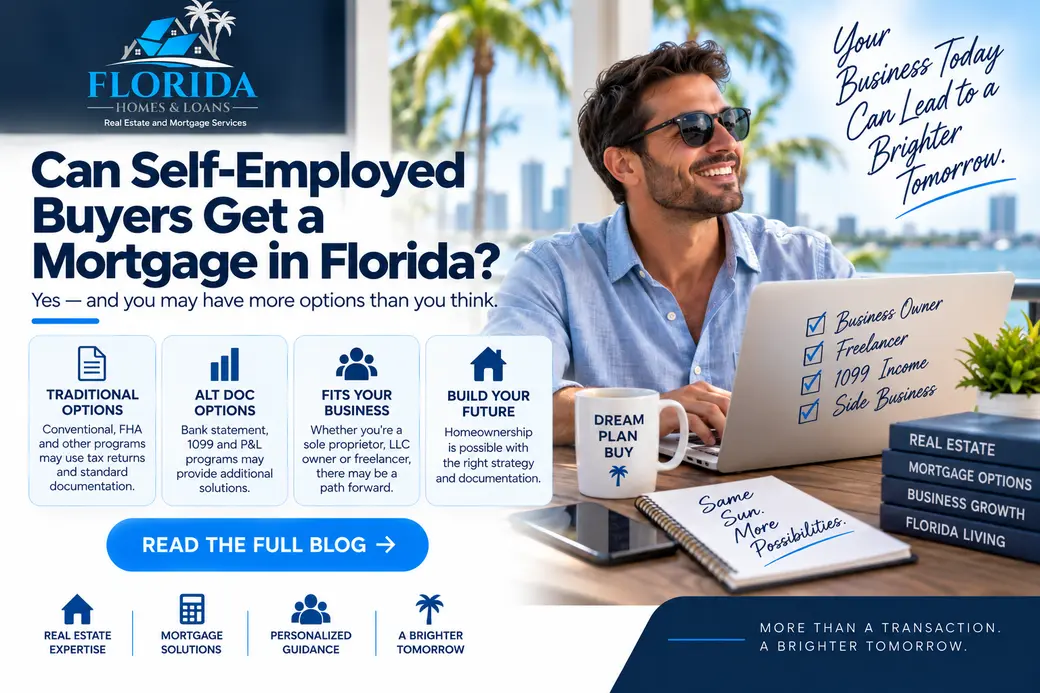
Yes. Self-employed buyers can qualify for a mortgage in Florida. The biggest difference is that lenders usually need to analyze the stability and history of the income being used rather than simply relying on a salary and W-2. Depending on your business, tax returns, credit, assets and the property you are purchasing, both traditional and alternative-documentation mortgage options may be available.
Who Is Considered Self-Employed for a Mortgage?
Mortgage underwriting does not look only at whether you call yourself a business owner.
Your ownership percentage, business structure and how you receive income can affect how the lender evaluates your earnings.
Self-employed borrowers can include:
- Sole proprietors
- LLC owners
- S-corporation owners
- Partnership owners
- Independent business owners
- Borrowers receiving substantial income through a business
The exact underwriting treatment depends on the mortgage program and the borrower's ownership and income structure.
Why Is Self-Employed Income Evaluated Differently?
A salaried employee may receive predictable income that can often be documented through pay stubs, W-2s and employment verification.
A business owner may have income flowing through several places.
For example:
- Business revenue
- Business expenses
- W-2 salary from the business
- Owner distributions
- K-1 income
- Depreciation
- Retained earnings
- Multiple business entities
For that reason, the amount deposited into your business bank account is not automatically the same as the income a traditional mortgage lender can use for qualification.
What Documents Might a Self-Employed Buyer Need?
Documentation depends on the mortgage program and the individual file.
A traditional mortgage may potentially require items such as:
- Personal tax returns
- Business tax returns when applicable
- Year-to-date profit-and-loss statement
- Balance sheet when required
- Business ownership documentation
- Verification that the business is operating
- Bank statements
- Additional documentation requested by underwriting
Not every borrower will need every document listed above.
Do Self-Employed Buyers Always Need Two Years of Tax Returns?
Not necessarily in every situation.
Mortgage programs generally want to establish that self-employment income is stable, supportable and likely to continue.
A longer history can make that analysis easier, but the required history and documentation can vary by mortgage program, business history and borrower circumstances.
Instead of assuming you need to wait two full years, have the file reviewed based on your actual employment and business history.
What If My Business Makes Good Money but My Tax Returns Show Less?
This is one of the most common challenges for self-employed buyers.
Business owners often use legitimate tax deductions to reduce taxable income.
Those deductions can also reduce the amount of qualifying income available when a traditional mortgage program relies heavily on tax returns.
A business may collect $300,000 in annual gross revenue.
That does not mean the borrower has $300,000 of qualifying personal income. Business expenses, deductions, ownership percentage and the way income is reported all need to be analyzed.
Can Some Business Expenses Be Added Back?
Potentially.
Traditional underwriting may allow certain qualifying non-cash or one-time expenses to be considered differently when analyzing self-employed income.
However, buyers should not assume that every business deduction can simply be added back to income.
The tax returns and business financials should be reviewed according to the applicable mortgage guidelines.
What Mortgage Options Can Self-Employed Buyers Use?
Conventional, FHA and Other Programs
These mortgages may use tax returns and traditional income analysis to determine qualifying income.
Non-QM Mortgage Options
Certain programs may evaluate income using bank statements, 1099 income, profit-and-loss statements or other permitted documentation.
The fact that a borrower does not qualify under one program does not necessarily mean there are no mortgage options available.
What Is a Bank Statement Mortgage?
A bank statement mortgage is an alternative-documentation program often designed for self-employed borrowers.
Instead of qualifying primarily from traditional tax-return income, the lender may analyze eligible deposits over a defined period.
Depending on the program, the lender may use:
- Personal bank statements
- Business bank statements
- A combination permitted by the program
When business statements are used, an expense factor may be applied to account for the cost of operating the business.
Requirements vary significantly between lenders.
Can 1099 Income Be Used?
Potentially.
Certain mortgage programs are designed specifically for eligible borrowers who receive 1099 income.
Depending on the program, the lender may analyze the borrower's 1099 history along with supporting documentation rather than relying on the same methodology used for a traditional salaried employee.
What About a Profit-and-Loss Mortgage?
Certain alternative-documentation mortgage programs may use a qualifying profit-and-loss statement under their specific underwriting requirements.
These programs can be useful for some established business owners whose tax-return income does not accurately reflect their current cash flow.
They usually have different pricing, down-payment and reserve requirements than traditional agency financing.
Are Alternative-Documentation Loans the Same as Conventional Loans?
No.
Bank statement, profit-and-loss and similar alternative-documentation programs commonly fall within the non-QM mortgage market.
They may have different:
- Interest rates
- Down-payment requirements
- Credit requirements
- Reserve requirements
- Prepayment terms where applicable
- Documentation standards
The advantage is that they may provide another way to document income for a borrower whose finances do not fit neatly into traditional mortgage guidelines.
Can an LLC Owner Get a Mortgage?
Yes.
Owning an LLC does not by itself prevent you from obtaining residential mortgage financing.
The lender may need to understand:
- Your ownership percentage
- How the company files taxes
- How you receive income
- Whether business funds are being used in the transaction
- Whether withdrawals could negatively affect the business
Business funds may sometimes be eligible for down payment or closing costs, but documentation and business-cash-flow analysis may apply.
What If You Own More Than One Business?
Owning several businesses does not automatically prevent you from qualifying.
However, each relevant business may need to be reviewed.
A profitable business cannot always simply offset concerns involving another business without the appropriate underwriting analysis.
This is another reason self-employed buyers benefit from starting the mortgage review before shopping aggressively for a home.
Should You Change Your Tax Returns to Qualify for a Mortgage?
Do not make tax decisions solely for the purpose of obtaining a mortgage without speaking with your qualified tax professional.
Instead, have your mortgage options reviewed before tax planning whenever possible.
This can help you understand how the lender is likely to view your business income without making unnecessary financial decisions.
Why Should Self-Employed Buyers Get Pre-Approved Early?
For a salaried borrower, income qualification can sometimes be relatively straightforward.
A self-employed file may require more analysis.
Starting early gives your mortgage professional time to determine:
- Which income can be used
- Whether tax returns are required
- Whether business returns are needed
- How deductions affect qualification
- Whether conventional or FHA financing works
- Whether a bank statement or other alternative program should be considered
- How much cash and reserves may be required
It is much better to answer those questions before finding the perfect house.
What Should You Avoid Before Applying?
Self-employed buyers should be especially careful about making major financial changes during the mortgage process.
Before moving large amounts of money or changing your business structure, speak with your mortgage professional.
Changes that can create additional documentation may include:
- Opening or closing businesses
- Changing ownership percentages
- Moving large sums between business and personal accounts
- Taking on new business debt
- Making large undocumented deposits
- Changing the way you pay yourself
These actions are not automatically prohibited, but they can affect underwriting and documentation.
Frequently Asked Questions
Yes. Self-employed borrowers can qualify for conventional financing when their income, credit, assets, property and overall file meet applicable underwriting requirements.
Not in every circumstance. Documentation and history requirements depend on the mortgage program and the borrower's business and employment history. Your individual file should be reviewed before assuming you must wait.
Potentially. Traditional mortgage qualification may be difficult when tax-return income is low, but certain alternative-documentation programs may provide other options for eligible self-employed borrowers.
Certain bank statement mortgage programs may permit qualifying income to be calculated from eligible business-bank-statement deposits. Program-specific expense factors and documentation requirements apply.
Potentially. Traditional and alternative-documentation programs may consider eligible 1099 income depending on the borrower's history and the specific mortgage requirements.
Yes. Owning an LLC does not prevent you from purchasing a home. The lender may need to review your ownership, income, business financials and any business funds being used for the transaction.
Alternative-documentation mortgages can have different pricing, down-payment and reserve requirements than traditional agency mortgages. The cost should be compared with the benefit of qualifying through a different income-documentation method.
Ideally, before seriously shopping for a home. Reviewing the income early provides time to determine which documentation method and mortgage program are most appropriate.
Your Business Income May Give You More Options Than You Think
Self-employed mortgage files are rarely one-size-fits-all. Florida Homes & Loans can review both traditional and alternative-documentation mortgage options to determine how your income may be used.
Whether you own an LLC, receive 1099 income, operate multiple businesses or have significant business revenue but lower taxable income, the first step is understanding the options before you start shopping.
This article is for general educational purposes only and is not financial, tax or legal advice. Self-employed income calculations and documentation requirements vary by mortgage program, lender and borrower circumstances. Alternative-documentation and non-QM programs may have different rates, costs, down-payment requirements and underwriting standards. Mortgage programs and guidelines are subject to change. This is not a commitment to lend. All financing is subject to borrower, credit, income, property and underwriting approval. Equal Housing Opportunity.
Categories
Recent Posts