Should You Ask the Seller to Pay Your Closing Costs?
Should You Ask the Seller to Pay Your Closing Costs?
Yes, a buyer can ask a seller to contribute toward allowable closing costs, and in the right transaction it can significantly reduce the amount of cash needed at closing. Whether the seller agrees—and how much can be contributed—depends on the offer, market conditions, mortgage program and applicable contribution limits.
What Are Seller-Paid Closing Costs?
Seller-paid closing costs, often called seller concessions or seller credits, occur when the seller agrees to use part of their proceeds from the sale to pay certain costs on behalf of the buyer.
Depending on the mortgage program and transaction, eligible costs may include certain:
- Lender fees
- Title and settlement charges
- Prepaid expenses
- Escrow deposits
- Discount points
- Mortgage-related closing costs
The amount a seller can contribute and the expenses the credit can cover depend on the loan program, occupancy, down payment and other factors.
Does the Seller Give the Buyer Cash?
No.
A seller credit is normally applied toward eligible costs on the closing statement. The buyer does not simply receive the agreed amount as cash after closing.
This is an important distinction when negotiating a large seller contribution.
Suppose the contract provides up to $10,000 toward the buyer's allowable closing costs, but the transaction only has $7,500 of eligible costs that can be covered. The buyer generally cannot simply receive the unused $2,500 as cash.
This is why the seller contribution should be reviewed with the mortgage professional before the offer is finalized whenever possible.
Is It Better to Ask for Closing Costs or a Lower Purchase Price?
It depends on what the buyer is trying to accomplish.
Many buyers automatically assume a lower purchase price will create the biggest financial benefit. That is not always true.
A relatively small price reduction may only produce a modest change in the monthly mortgage payment, while the same amount provided as a seller credit may substantially reduce the cash required at closing.
Imagine a buyer is considering a $400,000 property.
One option may be negotiating the price down by $5,000.
Another option may be keeping the purchase price closer to the seller's asking price while negotiating a $5,000 contribution toward allowable closing costs.
For a buyer who is comfortable with the monthly payment but wants to preserve savings after closing, the seller contribution could potentially provide more immediate value.
The numbers should be compared before deciding.
Can Seller Credits Be Used to Lower the Mortgage Rate?
Potentially.
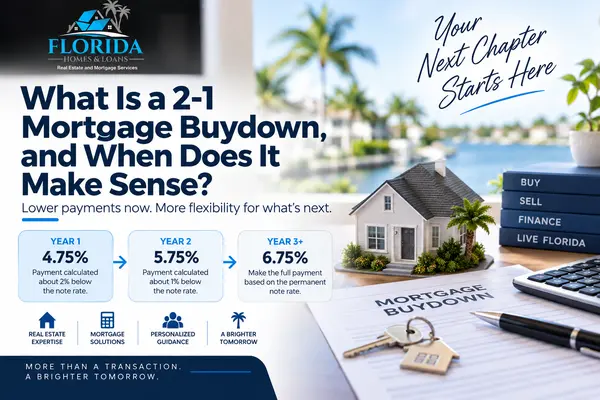
When permitted by the applicable mortgage program, seller contributions may sometimes be used toward discount points or an eligible temporary mortgage-rate buydown.
This can create several possible negotiation strategies:
- Reduce the purchase price
- Pay allowable buyer closing costs
- Use funds toward discount points
- Fund an eligible temporary rate buydown
- Address agreed-upon repairs or other permitted costs
- Use a combination of strategies
Which option provides the greatest benefit depends on the mortgage, the buyer's available funds and how long the buyer expects to own the property or keep the loan.
Why Would a Seller Agree to Pay a Buyer's Closing Costs?
Seller concessions are a negotiation tool.
A seller may be more willing to consider a contribution when:
- The home has been on the market for an extended period
- The seller has already reduced the price
- There are fewer competing buyers
- The home needs cosmetic improvements
- Competing properties are offering incentives
- The seller values the buyer's preferred closing timeline
- The overall offer still provides acceptable net proceeds
In a competitive multiple-offer situation, however, requesting a large seller credit may make an offer less attractive compared with another buyer asking for fewer concessions.
How Does the Seller Look at Your Offer?
Sellers do not necessarily focus only on the purchase price.
They are often interested in the amount they are expected to receive after the transaction expenses and negotiated concessions are taken into account.
For example, an offer at $410,000 with a substantial seller contribution may produce lower proceeds than a $400,000 offer with no requested contribution.
This is why purchase price and concessions should be negotiated together rather than independently.
Can the Appraisal Affect a Seller Credit?
Yes.
Sometimes buyers consider increasing the purchase price in exchange for a larger seller contribution.
That can work in certain transactions, but increasing the contract price does not automatically increase the property's market value.
If the transaction requires an appraisal, the property still needs to support the applicable value requirements for the mortgage.
If a home is realistically supported around $400,000, simply writing a contract for $415,000 so the seller can provide a large credit does not guarantee the home will appraise at $415,000.
Comparable sales and appraisal risk should therefore be considered when structuring the offer.
How Much Can the Seller Contribute?
There is no single contribution limit that applies to every mortgage.
The maximum permitted amount can depend on factors such as:
- Conventional, FHA, VA or other financing
- Down payment
- Occupancy
- Loan-to-value ratio
- Property type
- The actual amount of eligible closing costs
Buyers should avoid assuming that a certain percentage is available without confirming the requirements for their specific mortgage.
Should First-Time Buyers Ask for Closing Costs?
It may be worth considering, particularly when preserving cash after closing is important.
Buying a home involves more than the down payment.
After closing, a buyer may still need money for:
- Moving expenses
- Furniture
- Immediate repairs
- Appliances
- Insurance deductibles
- Utility deposits
- Emergency reserves
Using every available dollar simply to reach the closing table can leave a new homeowner financially stretched immediately after purchasing.
A seller contribution may help an eligible buyer preserve some of that liquidity.
Can You Ask for Both a Price Reduction and Closing Costs?
Yes.
A buyer can negotiate multiple terms in the same offer.
For example, an offer could request:
- A lower purchase price
- A seller contribution toward allowable closing costs
- A repair credit
- A particular closing date
However, every additional request affects the seller's view of the overall offer.
The objective should be to structure the strongest transaction for the buyer while still presenting terms the seller may realistically accept.
Frequently Asked Questions
Potentially, but the amount the seller can contribute and the costs that can be covered depend on the mortgage program, transaction structure and actual eligible closing costs.
Seller concessions generally cannot simply replace a borrower's required minimum contribution when the mortgage program requires the borrower to provide one. Program rules should be reviewed for the specific transaction.
Potentially. Certain mortgage programs permit seller-funded temporary buydowns or contributions toward discount points when the transaction meets program requirements.
Not always. A seller credit may provide greater immediate savings for a buyer who wants to reduce cash to close, while a price reduction lowers the amount being paid for the property. The two options should be compared using the actual mortgage numbers.
It can. Sellers typically consider their estimated net proceeds and the overall strength of the offer. In a less competitive market, however, seller concessions may be easier to negotiate.
Unused seller concessions generally cannot simply be paid to the buyer as cash. The contract and mortgage should be structured carefully so the requested credit is appropriate for the expected eligible costs.
Negotiate More Than Just the Purchase Price
At Florida Homes & Loans, we can look at the real estate offer and mortgage structure together so you can compare a price reduction, seller-paid closing costs, rate buydown and other available strategies before deciding what to request.
Sometimes the best deal is not simply the lowest purchase price. It is the combination that gives you the right home, manageable payment and comfortable amount of cash left after closing.
This article is for general educational purposes only and is not legal, tax or financial advice. Seller contributions, eligible closing costs and contribution limits vary by mortgage program and transaction. Mortgage programs, rates, terms and underwriting requirements are subject to change. All financing is subject to borrower, credit and property approval. Equal Housing Opportunity.
Categories
Recent Posts